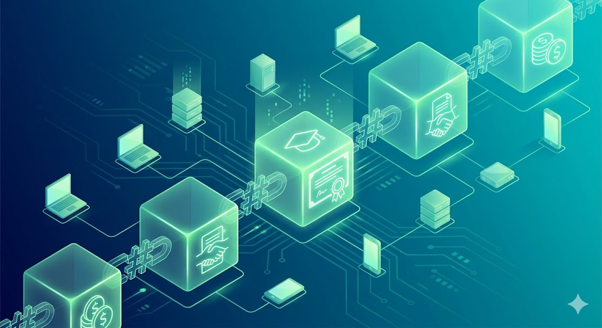
Although artificial intelligence currently dominates tech discussions, blockchain remains an important and widely discussed technology. At its core, a blockchain is a type of database used to record transactions. The main idea behind it is that each block of data contains a reference—a cryptographic hash—to the previous block, forming an unbreakable chain. Hence the name, “blockchain.”
How the chain works?
In a blockchain, data is stored in blocks, and each block has a hash generated from its specific contents. Each new block includes its own data and the hash of the previous block, permanently linking them together. This structure makes it extremely difficult to alter past records. Changing even a single piece of data in one block would change its hash, requiring a malicious actor to change all subsequent blocks to avoid detection. This makes system changes highly traceable and transparent.
Security and the “51% Attack”
Because any tampering is easy to detect, blockchain systems are generally considered secure. However, they are not completely risk-free. For example, networks are susceptible to a “51% attack.” In this scenario, a malicious actor who manages to control more than half of the network’s computing power could influence which new transactions are added. Even then, altering older, deeply buried transactions remains practically impossible. Therefore, blockchain is highly useful when a secure, automated, and decentralized database is needed.
Decentralazing Trust: Blockchain vs. Traditional Money
One of the most well-known uses of blockchain is Bitcoin. Bitcoin operates entirely on a blockchain. Although it has no physical form, its value comes from supply and demand, as well as the trust users place in the system.
Traditional money, such as euros or dollars, also relies on trust. Its value is not based on the material it is made from, but on the confidence people have in the governments and financial institutions that manage it. In the traditional system, banks act as trusted intermediaries that verify and record transactions. Blockchain replaces this centralized trust with a decentralized system. Instead of relying on a bank, transactions are verified and recorded by a distributed network of computers around the world, making the system transparent and highly resistant to single points of failure.
Different Types of Networks
Not all blockchains are exactly the same. The technology is generally separated into different network types based on access and control:
- Public blockchain: Open for everyone to join, like Bitcoin. While it provides true decentralization, it requires significant processing power to maintain the network and offers no transaction privacy.
- Private blockchain: Similar to public network, except a central administrator chooses who has the right to join. It has a smaller network size and can run inside a corporation’s own network using its internal firewall.
- Permissioned blockchain: A hybrid that can be both public and private. It generally requires an invitation or specific permission to join the network.
- Consortium blockchain: One shared network maintained by a group of organizations with equal responsibilities. This is ideal when different corporate parties need to cooperate securely.
The Takeaway: Why Should We Care?
While blockchain is often associated merely with crypto speculation, its real power lies in redefining digital trust. For students and future professionals, this technology goes far beyond Bitcoin. Imagine a near future where your university degree certificates, digital identity, or automated rental agreements (smart contracts) are stored on a blockchain—impossible to fake, alter, or lose. As society continues to digitalize, understanding decentralized systems is becoming a crucial asset. Whether you are studying business, IT, or law, blockchain is quietly setting the foundation for the next generation of secure, transparent internet services.